Report: Controlled Sale vs. Auction Sale of a Small Business

Report: Controlled Sale vs. Auction Sale of a Small Business

A Comparative Overview for Business Owners

By Thomas J. Perrone, CLU, CIC

1. Introduction

When selling a small business, owners typically choose between two primary approaches to engaging buyers: a controlled sale (also called a controlled or limited auction, or targeted negotiated process) and a broader auction sale. Both aim to transfer ownership, but they differ significantly in process design, level of competition, confidentiality, timeline, cost, and risk. The choice depends on the business’s size, industry, desirability, the owner’s priorities (price maximization vs. discretion and certainty), and market conditions.

This report outlines the key differences, advantages, disadvantages, and typical suitability for each method in the context of small businesses (generally those with revenue under roughly $50–100 million, though the principles scale).

2. Definitions

Controlled Sale

A structured but limited process in which the seller (usually through an advisor) identifies and approaches a select group of pre-qualified potential buyers—typically strategic competitors, complementary companies, private equity firms, or known industry players. Competition is created among this smaller pool under tight seller control over information release, timelines, and negotiations. It is not a free-for-all; the process is managed to protect confidentiality and maintain leverage.

Auction Sale

A more open competitive process designed to attract the widest reasonable universe of potential buyers. The business is marketed more broadly (via teasers, databases, industry networks, or public channels in some cases), with formal bidding rounds. The goal is maximum competitive tension so that the highest price and best terms emerge from the market. Pure “public auctions” are rarer for operating small businesses than for assets; most “auctions” in this context are still somewhat managed but far less restricted than a controlled sale.

3. Key Differences

The following table summarizes the primary differences between the two approaches:

Aspect

Controlled Sale

Auction Sale

Buyer Pool

Small, pre-selected, qualified group

Broad; many potential buyers invited

Confidentiality

High – limited disclosure, strict NDAs, controlled info flow

Lower – more parties see information; higher leak risk

Competition Level

Moderate (among few strong candidates)

High (designed for maximum bidding pressure)

Seller Control

High – over timing, process rules, information, and negotiations

Lower – market and multiple parties drive pace and dynamics

Timeline

Often shorter and more predictable

Can be longer due to broader outreach and more rounds

Cost & Complexity

Generally lower marketing costs; more focused effort

Higher marketing, coordination, and advisor costs

Risk of Disruption

Lower (employees, customers, suppliers less likely to learn)

Higher (rumors more likely to spread)

Price Outcome

Strong if right buyers are targeted; may leave some value on table

Potentially higher due to wider competition; not guaranteed

Deal Certainty

Often higher with well-chosen buyers

Can be lower if many tire-kickers or process fatigue occurs

4. Advantages and Disadvantages

Controlled Sale

Advantages:

  • Better protection of sensitive information and business relationships.
  • Seller retains more negotiating leverage and process discipline.
  • Reduced operational disruption and employee anxiety.
  • Often faster and less expensive to run.
  • Easier to manage for smaller businesses with limited internal resources.

Disadvantages:

  • May miss a higher-paying buyer outside the selected group.
  • Requires good advisor judgment in identifying the right targets.
  • Less pure market validation of value.

Auction Sale

Advantages:

  • Maximizes the chance of discovering the true highest bidder and extracting premium pricing or better terms (e.g., more cash at close, favorable earn-outs).
  • Creates strong competitive tension that can improve deal structure.
  • Provides clearer market feedback on valuation.

Disadvantages:

  • Greater risk of confidentiality breaches, which can harm the business if the sale fails.
  • Higher costs and management time.
  • Potential for process delays, “deal fatigue,” or lower-quality inquiries.
  • Can signal distress or desperation if not handled carefully.

5. Practical Considerations for Small Businesses

Small businesses are particularly sensitive to confidentiality because a single rumor can affect key employees, customer retention, supplier terms, or local reputation. For this reason, controlled sales are more commonly recommended and used for Main Street and lower-middle-market companies.

An auction-style process becomes more attractive when:

  • The business is highly desirable (strong growth, unique assets, or strategic fit for many players).
  • The owner prioritizes absolute maximum price above discretion.
  • There is a robust pool of both strategic and financial buyers.

Hybrid approaches are also common: a controlled process that expands the buyer list if initial interest is soft, or a “quiet” limited auction that maintains strict information controls.

6. Conclusion

A controlled sale prioritizes discretion, process control, and reduced risk while still generating meaningful competition among carefully chosen buyers. An auction sale prioritizes broad market exposure and maximum competitive pressure, potentially at the cost of higher risk and complexity.

For most small-business owners, a well-executed controlled sale strikes the better balance—protecting the going-concern value of the business while still pushing for strong economics. The optimal choice should be made with advice from an experienced M&A advisor or business broker who understands the specific industry, the company’s strengths, and current buyer appetite.

Note: This is a general explanatory overview based on standard practices in private-company transactions. Actual results depend on preparation of the business, quality of advisory support, market conditions, and execution.

LEARN MORE ABOUT US:

Download Free Report: Growing Your Business On Purpose

More on Growing your business, read this article

Four Pillars of a Strong Business: Growth , Protection, Transition, Equity

https://yourbusinessworth.com/2026/03/31/4025/

Thomas J. Perrone, CLU, CIC

203.530.6615
tperrone@necgginc.com

The Cheapest Way to Fund a Buy-Sell Agreement

By Thomas J. Perrone, CLU, CIC

Picture this: you and your business partner built something real together. Four million dollars in value, split fifty-fifty. Then, out of nowhere, your partner passes away. His widow now owns half your company. She doesn’t want to run it. She wants her money — now.

If that thought makes your stomach drop, you’re not alone. And here’s the uncomfortable truth: having a buy-sell agreement doesn’t mean you’re actually prepared for this moment.

Your Buy-Sell Agreement Is Only Half the Plan

Most business owners think a buy-sell agreement has them covered. It names a price. It names the terms. It says, in black and white, what happens when a partner leaves — through death, disability, divorce, or simply deciding to walk away.

But an agreement is only the what. It says nothing about the how. How does the money actually move from the surviving owner’s pocket into the widow’s hands? That question is where most buy-sell arrangements quietly fail — not in a courtroom, but at the bank, when it turns out the cash simply isn’t there.

Without a funded plan, owners are usually left with one of three bad outcomes:

– A fire sale — the business gets sold fast, often to a stranger, just to raise the cash.

– A forced partnership — you end up running the company with someone who never wanted to be your partner.

– The bank calls the loans — lenders get nervous about ownership uncertainty and tighten the noose.

None of that is good. And all of it is avoidable — if you fund the agreement properly, ahead of time.

The Three Ways to Fund a Buyout

Let’s use a simple example: a $4 million business, owned 50/50, with a $2 million buyout obligation. There are three real ways to cover that number.

Option 1: Cash

The instinct for a lot of owners is to just save up. Sounds responsible enough — until you run the numbers.

If your business generates $400,000 a year in distributable profit, split evenly, that’s $200,000 per partner. To fully self-fund a $2 million buyout, you’d need to set aside your entire share of profit for ten years. No raises. No reinvestment. No growth. Just money sitting there, doing nothing, in case the worst happens.

And here’s the problem nobody wants to say out loud: what if the event happens in year two? You’re $200,000 into a $2 million obligation, and your business has spent two years running on fumes because all its profit was parked in a savings account instead of working.

Cash funding only works in one scenario: if you never actually need it. The moment you do, it’s never enough.

Option 2: Borrowing

The next instinct is to borrow — a bank loan, or a note payable to the estate over time.

On a $2 million buyout, financed over ten years at 7%, you’re looking at roughly $28,000 a month. Over the life of that loan, total interest adds up to about $800,000 — money that leaves your business permanently and goes straight to the bank.

And the interest isn’t even the biggest problem. Borrowed money comes with strings: personal guarantees, the business pledged as collateral, and payments due no matter what — recession or not, lost customers or not. On top of that, a departing partner’s estate has little reason to accept a slow note when the agreement says they’re owed full value now. Notes get renegotiated. Disputes happen. And the business you’re trying to protect ends up in court anyway.

Cash starves the business. Debt mortgages it. Which brings us to the option that actually works.

Option 3: Life Insurance

Here’s the idea, and it’s refreshingly simple. You take out a life insurance policy on your partner. The business — or a properly structured trust — owns the policy and pays the premium. When your partner passes away, the death benefit arrives tax-free, within weeks. That’s your buyout, fully funded, on the spot. No fire sale. No note. No bank involved.

For a healthy partner in his fifties, a $2 million death benefit typically costs somewhere between $20,000 and $40,000 a year in premium, depending on how it’s structured.

Now compare that to the alternatives:

| Funding Method | Cost Profile | Key Risk |

  1. Cash (self-funded) | $200K/yr of profit for 10 years | Starves the business; badly exposed if the event happens early |
  2. Borrowing | ~$28K/mo; ~$800K in total interest | Collateral, personal guarantees, payments due regardless of performance |
  3. Life Insurance (trust-owned) | ~$20K–$40K/yr premium; full coverage from day one | Requires correct ownership structure and an insurable partner |

The number that tends to get people’s attention: a trust-owned life insurance approach runs roughly 74% less expensive than the next best option. And unlike cash, the coverage is fully in place from day one — not after a decade of saving.

How to Structure the Policy

Once you’ve decided insurance is the right tool, you still have to structure it correctly. There are two standard approaches.

Cross-purchase agreement. Each partner personally owns a policy on the other. When one dies, the survivor collects the death benefit and buys the deceased partner’s shares directly. Simple, clean, and it works especially well with two partners.

Entity purchase (stock redemption). The business itself owns the policies and buys back shares from the deceased partner’s estate. This tends to be easier to administer when there are three or more partners involved.

Which one is right depends on your entity type. C-corporations can run into alternative minimum tax issues under certain structures. S-corporations raise their own questions around ownership and basis. This is exactly the kind of decision that shouldn’t come from a template you found online — the structure you choose has tax consequences that can follow your family for a generation.

The Advanced Move: Trust-Owned Insurance and Key Person Coverage

If you want to do this the smart way, there’s a more sophisticated layer worth knowing about.

Irrevocable life insurance trusts. Instead of you or the business owning the policy, a trust owns it. Why bother? Two reasons. First, it keeps the death benefit out of your taxable estate — for owners with real net worth, that can mean millions in estate tax the family never has to pay. Second, the trust controls the timing and terms of the payout, so the proceeds go out exactly as the agreement says, instead of becoming a bargaining chip.

Key person insurance. This is a different tool entirely — it protects the business, not the ownership transfer. If you’ve got a key employee who runs operations or holds your most important customer relationships, their death would hit the business hard: lost revenue, lost relationships, a scramble to replace them. Key person coverage puts cash into the business to bridge that gap. It’s not for the buyout. It’s for survival. Any business with roughly five to fifty employees should have this on the radar.

Four Mistakes That Cost Owners the Most

1. Buying term insurance that expires. Buy-sell needs are permanent — you can’t predict the year something happens. Permanent coverage is the honest answer.

2. Getting the policy ownership wrong. If the person who owns the policy isn’t the same person who owes the buyout, the death benefit can trigger a tax problem and defeat the whole plan.

3. Letting the valuation go stale. The agreement says $4 million, but the business is now worth $9 million. That’s not a plan anymore — it’s a time bomb.

4. Assuming your partner is insurable. If there’s a health issue, you want to know now, while you can still get coverage — not after it’s too late.

What to Do This Week

You don’t need to overhaul everything today. Start here:

1. Pull your buy-sell agreement and ask the honest question: is this actually funded, or does it just look funded on paper?

2. Get a life insurance illustration on your partner. Just the numbers — no commitment required.

3. Have the conversation with your partner. It’s awkward, sure. But it’s a lot less awkward than the widow, the fire sale, or the bank calling your loans.

A buy-sell agreement is only as good as its funding. Of the three options — cash, borrowing, and life insurance — insurance, especially when trust-owned, is the one that’s cheapest, fastest, and most reliable when it actually matters. Get the funding question answered now, while everyone’s calm and thinking clearly, so the only thing left to work out later is the number.

Download your free BSA report Guide-  CLICK HERE

Check This Article called “Connolly Alternatives: 

Need to discuss:  Toms Calendar. 

Case Study: Rapid Sales Growth and Ownership

Case Example Using Term Insurance

By Thomas J. Perrone, CLU, CIC

This was a situation where the company needed protection but wasn’t ready to purchase permanent insurance, even though the situation called for it.  However, the term insurance gave them what they wanted at the time and gave them the needed protection. 

Scenario: 

 A thriving business, comprising three partners—a relationship builder, an idea generator, and a product engineer—experienced remarkable sales growth within a few years. However, a potential challenge arose regarding ownership transfer upon a partner’s death, as all partners shared familial ties. 


To mitigate this concern, a comprehensive stock redemption program was devised and funded through a term insurance policy with a premium exceeding $60,000. This strategic approach enabled the business to navigate ownership transfer complexities and ensure the continuity of its operations.

Through the years, parts of the term insurance has been converted, and the company is paying about $125,000 in insurance premium to fund their liabilities and commitment.  

The case was developed through a relationship i had with one of the owners, through an introduction.  

Lesson:  

Even though this was a start up and a young company, if I has assumed it did not have the cash flow, I would have lost out on all the great potential.  Don’t assume anything, but let your client tell you what they want and why. 

THE WHY: 

There was a past history of the one of the current partners where their family member was part of a company where the partner died.  No planning was done, so the deceased partners family became the new partners.  This was not pretty, and the business ended up in chaos.  Obviously, a motivating factor for the current owner to have a good Buy and Sell Agreement where it was funded 

If you are an advisor who is working with business owners or wants to develop a business market segment in your practice, we should talk. We offer great opportunities working with our organization and deep backup.  

Thomas J. Perrone, CLU, CIC

tperrone@necgginc.com

The Benefits Of Keeping Your Key Person And Key Group!


Recently, I wrote an article about the “Quintessential Employee” and covered all the benefits of having a key person in your company. 

The Education of the Quintessential Employee! 

Some of the attributes of the key person are:  

  • Creates more business value by freeing owners to focus on other profitable tasks 
  • Purchasers of a business want to have middle management in place 
  • Builds reputation and culture 
  • Key people tend to impress other employees as a good example 
  • Key people, as described, are also likely future purchasers of the business, or 
  • Likely to run the business while the owner enjoys life, but still has the control and wealth 

For the full article, download The Benefits Of Keeping Your Key Person And Key Group

Enjoy the download of the full article. The link in the article will download immediately the option of receiving the report.

Download The Article

Rushing Through the Most Important Document in Your Business!

In my career I have experienced several business owners rushing through the implementation stages of designing their buy and sell agreement (BSA), probably one of the most important documents they will ever need, treating the process with little thought.   As Rodney Dangerfield would say, “No respect”.  When it was completed, it was very basic, doing more harm than good. 

In some cases, maybe more than I think, the document being used by the drafting attorney was a “hand me down” from another attorney.  While the “hand me down form” may have been useful in drafting another person’s situation and making it easier for the drafting attorney to do, it was not going to maximize my client’s planning situation.

In Paul Hood’s great book, “Buy And Sell Agreements, Last Will And Testament For Your Business”, he covers the consequences of not designing the right buy and sell agreement, and how important it is to spend the time and money preparing and designing this important document, with an experienced lawyer.  [i]

Paul specifically speaks about attorneys using a “hand me down agreement”, and how it may be more harmful by having it than not. 

The “Paul Hood Fire Drill”

He uses the idea of the “fire drill”. What happens when a “trigger happens? What will be the outcome and the consequences based on how your BSA is set up (or not set up), when you play it out. Like you were the leaving owner, and then again as the remaining owner.  On a personal note, the “fire drill” advocated by Paul is something I use all the time and has been instrumental helping my clients and their attorneys in drafting the proper strategies for their situations.  I have found that this has been a great way of helping my clients design the best BSA for themselves. It has allowed them to make it real and start developing questions and ideas that they can implement in their design. It keeps them involved with the process.

The “Fire Drill” strategy has put my clients in the “power seat” of knowledge, so when they discuss their BSA with their attorney, the elements and strategies that are being used are not foreign to them. This consequently helps them design a better BSA, reducing the time needed to spend with their attorney ($$$$$).    

Keep in mind, many business owners start the process of designing the BSA when there has been no experience of consequences with an owner or co-owner leaving the company. 

Everyone is Equal at the Start!

When owners design their BSA, they are all equal in status.  People that enter into agreements want the agreement to favor them when a triggering event happens, even if the agreement has not been updated in years or there is no reference to the triggering event. 

When are clients initially design their BSA, it probably will be one of the few times that all the partners will be negotiating with each other, because when there is a triggering event, chances are they will be negotiating with someone other than their co-owner.  

The representative of the departing co-owner will have a different perspective as to what they want out of the BSA!  Whether it is the spouse, their child, their law firm, whomever, they will be negotiating from a different point of interest.

Business relationships, and friendships are put aside.  It is at this point you would hope your BSA covers all the areas of concern that need to be covered.  The bottom line is the agreement must be exact as to what will specifically happen based on the triggering event.  There is no room for errors if the document is specific.  The best time to do this is when everyone is on equal ground. 

For this reason, owners designing their BSA with their attorney should take it very seriously because they are really pre-negotiating for the people, they love the most without any certainty of which trigger will occur and which side of the trigger they will be on, leaving or a remaining co-owner.

It is extremely important that the triggering events be identified and that you will understand what will occur with each trigger event.  

Paul Hood’s “fire drill” has made it easier for my clients to understand the importance of designing a solid BSA.  By posing questions to the scenario, the BSA becomes very real to them.  

Examples of how they would play out the “fire drill”  

·       What if you’re the first co-owner to leave?

·       What if you’re the last remaining original owner? 

·       What if you end up with a co-owner you don’t want to be owners with? 

·       What happens if one of your co-owners, dies, divorces, or goes bankrupt?  

      By implementing your “fire drill”, you will start to formulate different scenarios for your own situation creating your own buy and sell design.  

This is a critical document in keeping your business going should a trigger happen to any of the co-owners.  Unfortunately, you must deal with it in advance and before there is a triggering event. 

Risks when implementing your BSA:  

·       Using an attorney who is using a fill in the blank form.

·       Not planning the scenarios before designing the plan. 

·       Not having a BSA.

·       Not signing it. 

·       No dealing with how to fund such triggers.  

There are so many elements to the buy and sell agreement that need to be covered, the planning of this document can’t be taken lightly.  However, that is not to say you can’t have a great BSA.  Having experienced professionals to help guide you through the process will pay off great benefits in designing and implementing your BSA. 

We suggest you find competent counsel who has experience in designing the buy and sell agreements and discuss your goals and objectives with them. 

Again, my best advice is pick up Paul Hoods book (“Buy and Sell Agreements, last will and testament for your businesss”.) Read and study it. 

 If you would like our free Business Succession and Transition Planning Guide, click the link and we will send you a FREE WHITE PAPER to get you started. in your planning.   YOUR FREE GUIDE


[i] E. Paul Hood is a prolific technical author. He has published a number of books on planning and is one of the leaders in estate planning and business succession planning.  

If you didn’t think you had to plan- Get ready to in 2022!

Over the years I have observed the inability of many business owners to plan their business and personal estate effectively, for one reason or another. Any excuse doesn’t matter, the bottom line is many (great majority of business owners) don’t have adequate estate and business financial plans. I have often referred to them as “plan by default”, as opposed to a “designed plan”. Guy Baker is were I first heard the terms this way. Very adequate considering the subject.

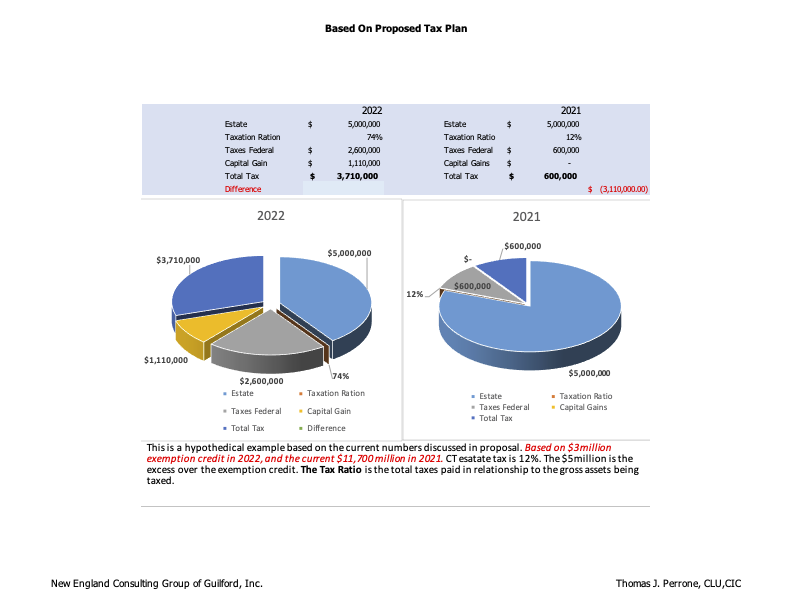
As you can see in the illustration below, when you consider the exposure of $5 million estate after exemption credits are use, you have the additional loss of the stepped up cost basis. There is a tax ratio of 74% vs. 12% in 2022 if some of the proposals go forth.

Image the business owner who has a high value property which has deferred gain locked in, and the results of that property when at death it is passed to the children?

Here is one of the reasons why business owners should pay attention.

zoom in.

Critical Step Needed To Create An Exit Strategy! Part 1 

Some business owners think that selling their business is a matter of getting an appraisal and putting the business on the market hoping for a good offer.

Many business owners that I have worked with initially assumed they knew the value of their business and what they could sell it for.

Through our education process they realized there is much more to selling their business, then just the establishing a value and then going to market.     One of those factors or variables is whether the business owner needs the business value for their future retirement, most do!

Helping the owner figure out what they need for retirement is critical in establishing what they need to sell their business for, and what action is needed to increase the future value of the business (Value Drivers).  In this article I will cover two of the seven steps that  are the most critical when planning a future exit from the business.

Whether the sale is one year or ten years from now, these are the steps needed to sell  a business.

  1. Must identify the Exit Objectives (why, when, and in some cases who) 
  2. Identify Personal and business financial resources; (this is part of the future financial security of the business owner and their family).  
  3. Maximize and Protect Business Value
  4. Ownership Transfer to Third Parties
  5. Ownership Transfers to Insiders
  6. Business Continuity
  7. Personal Wealth and Estate planning

In this post I will cover steps 1-3, and cover steps 4-7 in the June issue.  

In comprehensive Exit planning, (when you break the process down it looks like this):

Your Exit Objectives

  • Building and preserving business value
  • Selling your company to a third party
  • Transferring your ownership to insiders

Your Business and Personal Financial Resources

  • Business Continuity
  • Personal wealth and estate planning

Owner’s goals and aspirations are

  • Financial Need
  • Overall Goals
  • Value based goals
  • Defining the owner’s goals and aspirations shows the client’s wants and needs and identifies what is  important to the business owner. By spending time collecting this information from the business owner we establish a strong relationship, while differentiating you, and allowing you to be the quarterback of the plan.

Accurate information from the owner is critical to planning.      Calculating what the GAP of resources the owner needs to have in order to supply their future retirement income is critical.  It is here where the measurement of their resources helps to decide what they need to sell their business for, to help fund the gap.    Continue reading “Critical Step Needed To Create An Exit Strategy! Part 1 “

Single Appraiser vs. Multiple Appraiser Choices

This month I wrote about multiple and single Appraiser choice.  My friend Ed Pratesi was nice enough to give me some of his thoughts, which I definitely respect due to his experience and training.   Ed, thank you for this contribution.

Ed Pratesi wrote:

I read with interest your comments on Single Appraiser vs. Multiple Appraiser choices that owners have for a BSA. I agree in part with your assessment that the single appraiser choice is preferred but I do have a number of caveats and suggest that before the number of appraisers needed is secondary to choices made before this decision. Let me explain my thoughts:

Firstly, the choice of number of appraisers almost always works, whether one, two or the three step approach – except when it doesn’t!

Prior to the determination of the number of appraisers needed is preceded by what I refer to as the education process that a business appraiser must take the owners through in order to develop an agreement and a process that will likely be triggered when an unanticipated or unfortunate event has occurred.

In never ceases to amaze me that owners will spend money on creating a business plan, invest in physical assets and talent and not spend enough time on one of the most important events that will occur in their lives – either their exit or a partners exit. My complaint is not pointed at the owners but at the appraiser called in to initially called in to assist in the valuation.

My point simply is the an appraiser needs to explain the valuation process, the valuation methods used to value a business, the applicability or not of the methods to the company, a discussion of the definition of value – (for example fair market value or fair value, more on this in a later discussion), a complete discussion of adjustments that appraiser consider in the valuation process, and what discounts could apply and the reasons for application of discounts.

This part of the valuation process is more consultative and sets the framework for the conduct of an initial appraisal and of the work product. Finally, once the appraisal is complete a meeting to discuss the results and the process is essential and should be prefeaced with scenario planning should a provision of the BSA be triggered.

The goal is to get buy-in on the process not just the number!

I hope I have addressed part of the discussion of the number of appraisers – more to follow if desired…

Ed Pratesi

Edward E. Pratesi, ASA, CM&AA, ABV, CVA

Managing Director | UHY Advisors N.E., LLC
6 Executive Drive, Farmington, CT  06032
D: 860 519 5648 | C: 860 558 0453 | F: 860 519 1982

epratesi@uhy-us.com |  www.uhyvaluation.com

www.linkedin.com/in/ed-pratesi-140b762


Single appraiser Buy and Sell Agreement!

An alternative to the multiple appraiser agreement, is the single appraiser agreement (SAA).  There are two single appraisers’ processes. I

  1. Single appraiser, select now and value now
  2. Single appraiser, Select and Value at Trigger Event
  3. Single appraiser, Select Now and Value at trigger event

The preference is #1:

However, #2,3 are stopgap processes which can be used.  As mentioned in both of these types, the value is delayed to sometime in the future. 

Postponement of the appraiser selection and initial valuation create substantial uncertainties and potential for disagreements   or disputes.

The SINGLE APPRAISER, SELECT NOW AND VALUE NOW OPTION

In the BSA, the appraiser is named and is engaged to provide an initial appraisal for purposes of the agreement.

SELECT NOW: At the creation of the BSA, the appraiser is named. All parties have a voice and can exercise their choice as difficult as it may be.

VALUE NOW:  The chosen appraiser provides a baseline appraisal for the purpose of the agreement.  In this method, it is recommended that the value be presented in draft and give each party a time period for consideration before entering it in the final BSA. 

VALUE EACH YEAR (OR TWO) THEREAFTER:  This provides great advantages:[i]

  • Structure and process
  • Known to all parities
  • Selected appraiser is viewed as independent
  • Values are seen before triggering event
  • Since a draft will be provided to the participants, they can review for corrections to the mutual satisfaction
  • The appraiser’s conclusion in known up front and is the price until the next appraisal, or until a trigger event
  • Because the process is exercised at least once, it should go smoothly when employed at trigger events, less time consuming and less expensive than other alternatives

The single valuation process also helps the estate planning process with the annual reappraisals which will facilitate the estate planning objectives of the shareholders. For example, if the planning calls for minority discounts, the supplemental valuations at the not marketable minority level for gift and estate purposes.

[i] This type of valuation process will accommodate most small companies as for many reasons listed above. 


Life Insurance Proceeds In Business Valuations

If life insurance proceeds are considered as the funding vehicle, then the proceeds of the policy received following the death of a shareholder would not be considered a corporate asset for valuation purposes.(1)

It would be recognized that it was purchased for a specific purpose of funding the buy-sell agreement (BSA). IF it were considered a corporate asset, it would offset the company’s liability to fund the purchase of shares, added back as a non- recurring expense.

Treatment 1: (used as a funding vehicle, not a company asset)

Example: A company with a $10m value, has two shareholders, owning 50% of the company. The company holds a $6m life insurance policy on each owner (assuming no alternative minimum tax issues).

RESULTS: At Shareholder #1’s death, the company collects $6m of life insurance benefits. The surviving partner will receive $10m company value, and $1m of net tax-free proceeds, a total of $11m value. The deceased stockholder receives the $5m for the business.

Treatment 2: (A corporate asset)

Treating the life insurance as corporate assets for valuation purposes.

The proceeds are treated as a non-operating asset of the company. This asset along with other net assets, would be available to fund the purchase the of shares the of a deceased shareholder. Keep in mind that the expense of the deceased stockholder might be added back into income as a nonrecurring expense.  (2)

The treatment type can have a significant effect on the net position of a company or selling shareholder. There is also an affect in the ability of the company to purchase the shares of the deceased stockholder, and impact of the position of the remaining shareholders.

Company $10m, before $6m of life insurance. When you add the $6m into the value, the company value is $16m. The deceased shareholder entitled to $8m, the company pays $6m in life insurance proceeds and takes out $2m in promissory note.

RESULTS: The surviving owner, owns a company with 8 million and a note of $2 million.

Which treatment is fair? One owner ends us with $11m while the deceased owner, ends up with $5m. In treatment 2, the surviving owner has to carry a $2m debt to purchase the business. Two dramatic differences. A good reason, why the discussion should take place with your advisors.

More importantly, all parties should understand the ramifications of adding the life insurance proceeds in the valuation or using the life insurance as a specific vehicle to fund the BSA.

——————————

1. Mercer: buy and sell agreements for boomers

2. Non-reoccurring expenses: Non-reoccurring expenses can be somewhat more complex. These are expenses which is  specifically  designated on the company’s financial statements as an extra ordinary or one time expense.  The company does not expect to continue the expense overtime, at least not on a regular basis. Non-reoccurring expenses can be somewhat more complex.