“The Story of Retirement for The Business Owner” 

It is quite common for an employer to think in terms of a qualified retirement program when they think of retirement.  The benefits of having a company plan would be tax-deductibility, tax deferred, an employee benefit to help attract employees, and a host of other reasons to have one.  Most companies should have a long-term retirement plan for their employees. Most accountants will normally jump on this idea because it is another tax deduction.  

However, what is rarely discussed are the benefits that the owner of the company receives from the qualified retirement plan!   In most cases, the qualified retirement Plan will not be the best choice for the owner of the company, for various reasons.   

Here are a few disadvantages for the high-income business owner:  

  1. No control of deposit amounts  
  1. Limited contributions 
  1. Government controlled IRS FILING 
  1. Administration costs- actuarial costs, filing, accounting 
  1. Employer is the fiduciary is having responsibility and accountability to the plan (what happens when the employee loses money in the market?) 
  1. After-tax cost and non-recovery of the net outlay for the company 
  1. The percentage of payout for the employer is usually a much smaller percentage compared to the employees when they retire, so the employer owner is being discriminated against  
  1. The withdrawal is 100% taxable on all the funds 
  1. Tax exposure and penalty for using the funds before 59 ½.      
  1. Forced distribution RMD 
  • For the employee, having a 401k and/or profit-sharing plan is a great deal.  They could have matched contribution’s ability also.  It is probably one of the best ways for people to save for their retirement.   
  • The business owner or highly paid executive has the problem of creating enough capital for retirement so it can produce enough income to narrow the gap between their final pay and retirement needs.  In most cases, because of the limits imposed on qualified plans and the taxability of the withdrawals, the qualified plan will not be the answer.   
  • High Earning Business Owners – it’s a different story! 
  • However, for the high earning employer, this is not a great deal compared to other executive compensation plans the employer could be. implemented for them.  There are several major pension destroyers for the employer when comparing retirement plans vs executive compensation plans.  
  • Disadvantages of a qualified retirement plan to the “high earning business owner”, compared to using a CEEP! 

  • Limited contribution amount 
  • 100% of withdrawal taxable at retirement – With a CEEP you control the contribution amount 
  • Pre 59 1/2 with penalty.  
  • Funds in a qualified contribution plan would be very hard to extract (hardship clauses) 
  • Bottom line, when the employer needs funds to build inventory, buy equipment, payroll, retirement funds are not a source, however, in a private executive compensation plan, they would be.  
  • With a CEEP you have access to funds without a penalty 
  • Death benefit; limited to accumulated fund, and taxable in a pension.  
  • With an executive compensation plan like the CEEP, the death benefits are tax-free and large 
  • CEEP would have a large tax-free death benefit to finish the retirement that wasn’t even started, and the benefit would be tax-free 
  • Deductible:   
  • Contribution plans are tax deductible as the contributions are made, consequently showing a charge to earnings in the year of contribution.   
  • CEEPs are balance sheet friendly as a receivable asset with interest.  
  • CEEPs can be cost recoverable for the company, while retirement contributions are not. The qualified pension contributions are normally tax-deductible when made, but not recoverable for the company.  
  • With a qualified plan, you are forced to take RMD (Required minimum distributions) 
  • With CEEP, you are not.  CEEPS distributions are tax-free. 

Table below: A qualified contributory plan doesn’t do the job when the owner of a company has an interest in growing wealth through their business.  As mentioned, the contribution must be shared with the other employees, and there are rules as to the maximum contribution which high earners can make.  In this case, the owner only could put the $30,000 in their account. With the CEEP Executive Compensation plan, the full $50,000 could be deposited into the account of the owner of the company! 

Plan Contribution Future Value 66 Gross 15 payout Taxes YRLY Net Income 
Qualified 30,000 893,351 80,348 24,104 56,244 
CEEP 50,000 1,863,708 165,099 0 165,099 

Many advisors including accountants, lawyers, and financial professionals are not aware of some of the great programs that can be designed using executive compensation.  The CEEP program (Corporate Executive Equity Plan) is a flexible design built around the tax code.   

Here is a chart comparing a Profit-Sharing Plan/401k and a specially designed CEEP Executive Compensation Plan.  

ITEM PROFIT SHARING 401K CEEP 
Tax deductible Yes Yes, optional 
Tax deferred growth Yes Yes 
Government Controlled Yes No 
Selective as to Participants No Yes 
Pre 59 1/2 availability  No Yes 
Tax Free withdrawal No Yes 
Death Benefit Only current accumulated value of account, taxable Immediate substantial tax-free benefit 
Required Minimum Distribution Yes  No 

Bottom line:   

Contributory plans like 401k’s, SEPS, simple plans and IRA are wonderful plans for employees to save money for their retirement.  However, given the above list of restrictions for employers, they are not effective for high income business owners in my opinion.   

Note:   I used 30% marginal bracket. Over a 15-year payout, the pension would have a $361,560 tax liability, while the CEEP was tax free.

To learn more about The Small Business Super Retirement Plan Just for Business Owners and High Earning Executives, request our free White Paper. CLICK HERE! 

Someday You Will Leave Your Business By Retirement, Death, Disability Or Drop Dead At Your Desk! Do You Have A Method Of Taking Your Business Equity With You In A Tax Efficient Way?

There are millions of small businesses in the United States, and many of them have something in common, and that is that they do not have a succession plan.  

I have heard figures like 80% or higher do not have a succession plan. Over 50% of the companies that have a succession plan, have either outdated plans, or incomplete plans.  

Why is this an over whelming problem with small business owners? Why would a business owner not want to make sure their “lifetime of effort” isn’t lost because of a lack of planning? 

SCENARIO: Someday all business owners will leave their business, either by retirement, death, disability, or just drop dead at their desks.  

 There will be a great loss in the value of the company because of this lack of planning, and consequently, the owner or the family will not receive the true potential value of the business. 

While I cannot explain why business owners do not do their planning, I can tell you some of the reasons the business owners and their family will not get the true value of their company when one of the three triggers occurs (retirement, death, and disability) They would be: 

Lack of planning -. They do not implement systems such as value drivers’ systems, next middle management, systematizing procedures, and others business building procedures. These are the elements that create the future value which a purchaser looks for when buying a business. 

The lack of planning also includes the failure to develop a middle management which could take over most of the tasks of the owner. By not creating a middle management, it leaves the owner as the indispensable person, the essential person in the firm. This is a dangerous position for the future of the company. It may be the greatest threat to the future value of the business.  Like anything else, when you lose the essential indispensable part of a machine, the machine will not work.  This is the same for the company when the owner is the “essential and indispensable” employee.  

Time- Most systems need time to develop and cultivate when building a business. Processes and systems need years to mature and create the potential value of the company. Consequently, when the owner gets near retirement with no more road left to plan, it is too late. Selling the business at the most potential value is not attainable. 

No liquidity: Many business owners put too much of their wealth in the business, such as inventory, machinery, receivables, and benefits, to name a few. They do not make the adjustment to using business cash flow to create wealth outside of the business, like pension plans, executive compensation plans, and other value building programs. Consequently, when capital is needed, it is hard to raise it, and is not readily available to the owner when needed the most.  

When business owners, decide they want to retire, and leave their business, they find themselves in a conflicted position. Because they did not take the time to plan, they have run out of time, and they will not yield the value they would have normally received if they had done planning over the years.  

The only options they may have:  

  • Sell at a reduced price 
  • Stay in the business until they find a buyer willing to buy at this price 
  • Continue in the business to fund their “retirement years” 

The bottom line is to start your planning early. My suggestion would be on the day you buy or start your business, start implementing a transition plan, as most of the transition planning requires an extended period in order to implement.  

Get your free Business Transition Commonly Asked Questions Report! Click here! 

Unknown Ways You “Shipwreck” Your Business!

This blog post is for the business owners who want to make sure their planning is solid and won’t shipwreck their businesses, estates, and legacy.  However, because of past experiences dealing with some professionals, their planning is incomplete, and they have put their financial planning on hold.  In summary, they are motivated to make sure they have good plans but are frustrated with the system of getting their planning efficiently completed.  

Throughout my career I have often wondered why business owners put things off that should not be delayed, as the price of doing nothing can be very costly. Ask any attorney how many unsigned wills they have in their file cabinets and watch them roll their eyes.

I have concluded owners end up with incomplete plans because of the way some professional advisors work with the business owners [1].   

  1. Advisors have their own agenda and put the business owner’s aside.
  2. Advisors don’t work together to share knowledge about the business owner to maximize the effectiveness of the planning. 
  3. They protect their territory and don’t share information.
  4. They make planning more complicated than it needs to be.
  5. They are not good listeners.  
  6. They tell the business owner, as opposed to asking, them what they want. 
  7. Brevity- Business owners really like to get things done.  Advisors in many cases are not efficient time managers when it comes to presenting ideas to business owners.  
  8. Many advisors come to meetings without preparation and wing it. 
  9. In some cases, business owners don’t trust their advisors. 
  10. Some advisors are not open to educating themselves in other planning areas, and neglect bringing in a specialist for the purpose of protecting their planning turf. Consequently, the business owner never gets exposed to the planning that needs to be done. 

 Keep in mind that most business owners have many opportunities to plan, however, they are frustrated from their past experiences and give up, never getting their plans completed.   

Communication with the business owner

Business owners are busy people.  To get their attention requires communication skills. 

Business owners are looking for someone they can trust to get these things done.   Someone they can rely on, and someone who will take the time to really understand what it is that they want and need to do in their planning.  

Your Ears

You have two ears and one mouth. Get it?   By asking poignant questions and listening, you can learn much about the business owner. Let me show you by an example.  Recently I was referred to, and helped, a business owner named Bill. Bill was frustrated that he hadn’t done particularly good planning. 

Our first conversation was about estate planning. I asked him, “up to now, what has been the extent of your estate planning”? He said he had a will but did it many years ago. 

I asked him if he knew who Doris Day was, and told him a story of when Doris Days’ husband died (he was her manager and took care of every detail in her life), she found herself in a huge dilemma. You see, she never bothered to know anything about her business arrangements. She avoided the business part of her life. She left it up to her husband 100%. He died in his 40’s of a heart attack. Because she did not have any knowledge of the personal estate and business estate arrangements, she ended up owing a fortune to the IRS in income and estate taxes. 

Bill, “I am sure the last thing you want to happen is to have your wife end up being like Doris Day.” He agreed. 

“How much do you discuss estate planning with your spouse?” Followed by the question “Do you have an estate equalization plan for your children”?   Our discussion lasted over an hour, while I asked questions and took notes.

How many business owners do you know who died at the right time? In other words, they die when they start things (new loans for expansion), or in the middle of things like expanding key groups in the business, but they never seem to die after they finished something. 

They never die at a good time, and because of that, they normally have chaos in their estates, causing hardship during the estate settlement phase, costing much more to settle their estates. 

My question to Bill was, “Someday you will leave your business by death, disability, or retirement”.  What plans have you made to take your equity of your business with you in a favorable manner”? 

You see most business owners haven’t planned for this transition. When the time comes to retire, they can’t get their money out of the business, they don’t have any updated plans, and they have no time to adjust. Consequently, their “Lifetime of effort” is stuck in the business. If they tried to sell it, they wouldn’t get the true potential value from the business, because of a lack of planning.  Normally they want out and end up selling at a discount. They don’t have time to create a better value because they have run out of time. They haven’t done the necessary planning to build systems in the business to increase market value.

The business poured out the gravy!

By the time they want to retire, they have been used to a nice lifestyle, supported by the business.  This may include the social club, lunches, luxury vacations, entertainment, and in other areas of their life.

Because they can’t get the value they need out of the business, they are forced to stay in the business and hope it can continue being profitable, even though the business owner doesn’t have the heart to run hard any longer. In most cases, the business owner is trapped in their own creation. [1]     

Building value in your business takes a long time to create the systems and strategies to maximize the fullest potential value.  Unless the business owner takes the time to discuss this with advisors, implement value drivers and systems needed; they will never realize the greatest value of their business.  

 As Bill and I talked, he realized the story of his business and future needed to change. 

My story is really about business owners that pour a “lifetime of effort” in their business but don’t put the necessary time and consideration in how to get their “lifetime of effort” out of the business when they or their family need it the most.   

The business poured out the gravy!

By the time they want to retire, they have been used to a nice lifestyle, supported by the business.  This may include the social club, lunches, luxury vacations, entertainment, and in other areas of their life.

Because they can’t get the value they need out of the business, they are forced to stay in the business and hope it can continue being profitable, even though the business owner doesn’t have the heart to run hard any longer. In most cases, the business owner is trapped in their own creation. [1]     

Building value in your business takes a long time to create the systems and strategies to maximize the fullest potential value.  Unless the business owner takes the time to discuss this with advisors, implement value drivers and systems needed; they will never realize the greatest value of their business.  

 As Bill and I talked, he realized the story of his business and future needed to change. 

My story is really about business owners that pour a “lifetime of effort” in their business but don’t put the necessary time and consideration in how to get their “lifetime of effort” out of the business when they or their family need it the most.   

The Indispensable Owner

 The problem was that nobody else knew what Bill knew. Nobody would know what to do if something happened to Bill.  He was an indispensable owner and an essential employee.   He knew the clients, vendors, bankers, advisors, and the key people he needed to know to run his business.  

I told him that when a motor loses its “indispensable and essential part”, the motor will not run any longer.  I told him when he dies, retires, becomes ill, and leaves his business, the “indispensable part” will destroy his “lifetime of effort”.  

That resonated with Bill.  We are now working on building a middle management and putting together an estate plan and a succession plan.  

MESSAGE TO PROFESSIONALS:  

When dealing with business owners keep in mind that they are focused.  They don’t like complexity, and they want to completely understand everything before they make any decisions on issues.  Listen to them and ask them questions.

To Business Owners

Business owners make a big mistake by not putting in the effort and being aware of the other parts of their business.  They don’t need to learn it, but they need to be aware of it.  By not being aware of certain parts of business planning, they end up in a financial chaos situation. 

The solution is to have discussions with your advisors regularly about the different areas of your business that you are not involved in.  Such as; succession planning, estate planning, keeping your key group, executive compensation plans.  These are areas that need to be reviewed and considered.   Without them you will “shipwreck” your family legacy or create missed opportunities. 

In my practice I have set up a bi-monthly sessions to cover issues and topics for our business owners.  This keeps them up to date and gives them a resource to address other issues.  


[1] If he sold his business, paid all the taxes and fees (which would reduce his net value by about 40-50%), and then took that value and invested it at 3-4% (to avoid taking risks), his return would probably be much less than the perks and income he was taking from the business.  And that is what provided his lifestyle.  


Request your Free Harvard Bundle Reports, A White Paper “Business Essential” and your Business Guide to help you grow your business.

Tor receive it, CLICK HERE

[1] Professional financial advisors (anyone who is giving financial advice to business owners)

LISTEN to my podcast and feel free to share it with others.

https://podcasts.apple.com/us/podcast/building-and-protecting-your-business-worth/id1539791693

The Costly KNEE JERK FINANCIAL SUGGESTION!

Over the years, I have been asked by business owners how they can use their company to create more tax deductions and to build retirement funds for themselves. When you put tax deductions and retirement funds in the same sentence, it suggests the vanilla response, of a pension plan of some type or a contributory retirement plan, like a profit-sharing plan, or a 401k. 

However, is that what a business owner is really asking? Or, do they mean, they would like to build retirement funds through the business and assume they can get tax deductions? Or do both elements co-exist in the plan that they are thinking of? I think most advisors would suggest a 401k plan, a cash balance plan, a simple plan, or a profit-sharing plan for example. 


 This is what I call the costly, KNEE JERK REACTION. When asked by a business owner, about retirement plans, I have learned to slow it down and ask the business owner to clarify exactly what they are trying to accomplish, rather than rattle off a KNEE JERK response, such as a “profit sharing plan, or 401k plan”. 

Questions like:  

–      Do you want to include everyone in the plan? 

–      Do you only want to favor yourself and family? 

–      Are you trying to give a benefit to a specific employee?

Do you want all the contributions to end up in your account, or are you willing to share with other employees? If so, how many and who?

If the employer/employee is trying to stockpile contributions to their account, they will have limitations with money purchase plans (limitations on contributions for 2022 of $58,000.) This makes it hard to deposit substantial amounts of money into the employer’s individual account, since they must include everyone. 

Based on the response, this will determine how I design the plan. If he wants to spread the dollar among the group, you are talking about a qualified retirement plan. On the other hand, if they want limitations as to who can be involved, they are speaking about a non-qualified executive compensation plan. 

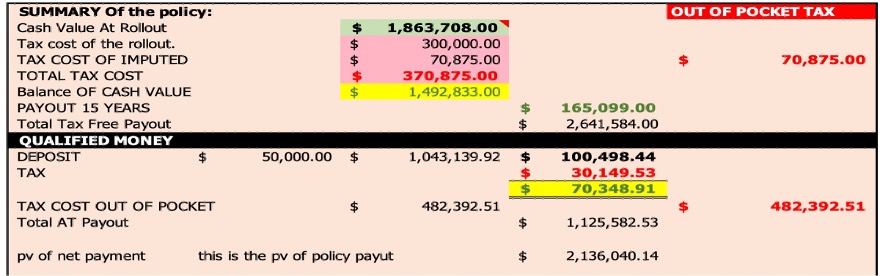
In this model, I compared two scenarios so my client would have an idea of the difference in absolute dollars. I based the model on conservative values and returns, staying consistent with both types of plans. I am comparing a CEEP to a Hypothetical Pension plan (money purchase plan). [i]

As you can see in the chart below, based on the same parameters for each plan, the CEEP program created much more retirement benefits for the owner than a qualified retirement plan. 

The owner participant received a much higher payout (tax-free), than the pension plan. In addition, if the owner died, from day one, the CEEP plan would pay a substantial tax-free amount to the family, while the qualified plan would only pay what was in the account which would be taxable to the beneficiary. The CEEP death benefit would be 100% tax free and would not be required to be withdrawn at death, or older ages like a pension or IRA plan would. 

Once you compare a CEEP to the Pension plan, you can then see why defining exactly what the owner wants to accomplish is important as both plans offer different benefits and different tax scenarios. 

KNEE JERK advice happens more than you think! And when it does, it can cost your client a lot of money, NOT to mention your reputation as an advisor. 

In this case, the “Knee Jerk” suggestion to use a pension plan to solve the problem, shortchanged the business owner from having greater benefits for the future when compared to the suggested pension plan. 


[i] In this scenario, the owner could only put in $30,000 of contribution out of the $50,000.  Based on a five many company and different salary ranges. 

REQUEST our free Business Essentials Report.  This report is more than a report, it is a resource and guide to many planning ideas for business owners.  It is an immediate download CLICK TO RECEIVE. 

Awareness to succeed!

This is the video and the narrative to post

This video is a 19-minute quick course which I put together in order .to share with you the biggest mistakes business owners make.

I call this the “Awareness to Succeed,” course. 

Owners spend most of their time on their product and services, and employee relations. This takes up much of their time. 

However, because of these time-consuming tasks, they are unaware of the other areas of business that should be understood and focused on by them, or at least have an awareness of. 

By not having some type of awareness in these areas, they run the risk of being side swiped by some fiscal impact that may have a major effect on their finances, both business wise and personally. 

This quick course will make you aware of some of the major areas you need to understand better. 

As an owner, you may not have the time to learn all that you need to know about these areas. You will learn that they are especially important and assign a professional consultant to keep you informed of your status and future developments in these areas. 

There are many changes coming out of Washington weekly that affect your business. You need a system to stay up on many of the changes. This course is designed to help you understand critical information. Take the 19 minutes to learn more about, Growth, Protection, Equity, and Transition in your business.

Once you complete this course, request a FREE download of my book “Unlocking Your Business DNA,” and subscribe to “Building and Protecting Your Business Worth Podcast.”  These are two great areas for learning. 

Request The Book: https://www.allclients.com/Form2.aspx?Key=DEC5C5C207C9803747A0458C9EB2D7C6


Subscribe to our podcast. 

https://podcasts.apple.com/us/podcast/building-and-protecting-your-business-worth/id1539791693

Rushing Through the Most Important Document in Your Business!

In my career I have experienced several business owners rushing through the implementation stages of designing their buy and sell agreement (BSA), probably one of the most important documents they will ever need, treating the process with little thought.   As Rodney Dangerfield would say, “No respect”.  When it was completed, it was very basic, doing more harm than good. 

In some cases, maybe more than I think, the document being used by the drafting attorney was a “hand me down” from another attorney.  While the “hand me down form” may have been useful in drafting another person’s situation and making it easier for the drafting attorney to do, it was not going to maximize my client’s planning situation.

In Paul Hood’s great book, “Buy And Sell Agreements, Last Will And Testament For Your Business”, he covers the consequences of not designing the right buy and sell agreement, and how important it is to spend the time and money preparing and designing this important document, with an experienced lawyer.  [i]

Paul specifically speaks about attorneys using a “hand me down agreement”, and how it may be more harmful by having it than not. 

The “Paul Hood Fire Drill”

He uses the idea of the “fire drill”. What happens when a “trigger happens? What will be the outcome and the consequences based on how your BSA is set up (or not set up), when you play it out. Like you were the leaving owner, and then again as the remaining owner.  On a personal note, the “fire drill” advocated by Paul is something I use all the time and has been instrumental helping my clients and their attorneys in drafting the proper strategies for their situations.  I have found that this has been a great way of helping my clients design the best BSA for themselves. It has allowed them to make it real and start developing questions and ideas that they can implement in their design. It keeps them involved with the process.

The “Fire Drill” strategy has put my clients in the “power seat” of knowledge, so when they discuss their BSA with their attorney, the elements and strategies that are being used are not foreign to them. This consequently helps them design a better BSA, reducing the time needed to spend with their attorney ($$$$$).    

Keep in mind, many business owners start the process of designing the BSA when there has been no experience of consequences with an owner or co-owner leaving the company. 

Everyone is Equal at the Start!

When owners design their BSA, they are all equal in status.  People that enter into agreements want the agreement to favor them when a triggering event happens, even if the agreement has not been updated in years or there is no reference to the triggering event. 

When are clients initially design their BSA, it probably will be one of the few times that all the partners will be negotiating with each other, because when there is a triggering event, chances are they will be negotiating with someone other than their co-owner.  

The representative of the departing co-owner will have a different perspective as to what they want out of the BSA!  Whether it is the spouse, their child, their law firm, whomever, they will be negotiating from a different point of interest.

Business relationships, and friendships are put aside.  It is at this point you would hope your BSA covers all the areas of concern that need to be covered.  The bottom line is the agreement must be exact as to what will specifically happen based on the triggering event.  There is no room for errors if the document is specific.  The best time to do this is when everyone is on equal ground. 

For this reason, owners designing their BSA with their attorney should take it very seriously because they are really pre-negotiating for the people, they love the most without any certainty of which trigger will occur and which side of the trigger they will be on, leaving or a remaining co-owner.

It is extremely important that the triggering events be identified and that you will understand what will occur with each trigger event.  

Paul Hood’s “fire drill” has made it easier for my clients to understand the importance of designing a solid BSA.  By posing questions to the scenario, the BSA becomes very real to them.  

Examples of how they would play out the “fire drill”  

·       What if you’re the first co-owner to leave?

·       What if you’re the last remaining original owner? 

·       What if you end up with a co-owner you don’t want to be owners with? 

·       What happens if one of your co-owners, dies, divorces, or goes bankrupt?  

      By implementing your “fire drill”, you will start to formulate different scenarios for your own situation creating your own buy and sell design.  

This is a critical document in keeping your business going should a trigger happen to any of the co-owners.  Unfortunately, you must deal with it in advance and before there is a triggering event. 

Risks when implementing your BSA:  

·       Using an attorney who is using a fill in the blank form.

·       Not planning the scenarios before designing the plan. 

·       Not having a BSA.

·       Not signing it. 

·       No dealing with how to fund such triggers.  

There are so many elements to the buy and sell agreement that need to be covered, the planning of this document can’t be taken lightly.  However, that is not to say you can’t have a great BSA.  Having experienced professionals to help guide you through the process will pay off great benefits in designing and implementing your BSA. 

We suggest you find competent counsel who has experience in designing the buy and sell agreements and discuss your goals and objectives with them. 

Again, my best advice is pick up Paul Hoods book (“Buy and Sell Agreements, last will and testament for your businesss”.) Read and study it. 

 If you would like our free Business Succession and Transition Planning Guide, click the link and we will send you a FREE WHITE PAPER to get you started. in your planning.   YOUR FREE GUIDE


[i] E. Paul Hood is a prolific technical author. He has published a number of books on planning and is one of the leaders in estate planning and business succession planning.  

The Education of the Quintessential Employee!

My friend of fifty-four years, George, is a very remarkable person. In a recent conversation I had with him, I realized that George defines the “quintessential employee.”  Why? He makes the “quintessential employee” easy to spot. Just follow him around when he works.

As George was telling me about his history with his company, he related how the company owner came to visit him unexpectedly to thank him for his service of 29 years. When I asked him why he thought the owner appreciated him, he described for me all the things he did over that period. 

Consequently, what George told me was the definition of the “model key person.” A person that every business owner wants, and needs, in their organization. 

You can spot a model employee in a heartbeat because:

They are the first ones to come to work. They almost never take time off. They volunteer time when needed to cover for others. They learn more than they must and are eager to learn. They are so good at their job (s) you would think that they were the owner. 

Key employees like George are valuable for the owners because, they always make life easier for the owners. Key people bring so much to the table, and are the most valuable asset in a company. 

Intrinsic rewards examples in the workplace

Below are some intrinsic rewards that may affect your workforce. Fostering these activities and feelings in the work environment could help your team grow and thrive. A key person exemplifies these values. 

  • Completing meaningful tasks
    • Letting employees be selective
    • Gaining a sense of competence
    • Making noticeable progress
    • Feeling inspired to be more responsible
    • Being an important part of an organization or team
    • Feeling accomplished
    • Feeling pride

I have frequently suggested to many business owners that they groom talented people in their firms who have the take charge values and attitudes which parallel the owner’s. They normally get it, want it, and can do it. 

A key thing an owner can do is to surround themselves with like-minded and value driven employees and build from there. The key person has the values of the owner, and the key person influences other workers over time. They set the example of the company’s culture and the value of the owner and the company. 

Two Questions:  

  1. How do you find such a person? 
    1. How do you keep them? 

Finding is the hard part, keeping is the easy part.

Finding the right person really comes down to the culture which the company portrays to the public. Like Costco or Trader Joe’s, who have the reputation of a wonderful place to work. They continually enhance their reputation of wonderful places to work. By having a well-known culture, companies attract like-minded individuals. Also, having the sense of value, the company can immediately filter applicants who apply for a position. Knowing the company values, is a built-in filter and a screening tool for the company when hiring. Question: “Can this person develop into a key person”? And “Does this person have the values that represent this company?”

Small family businesses can build that type of culture by hiring based on value, creating good compensation, benefits, giving respect to workers, positioning them in the right seat, (also taking them out of the seat if it does not fit, and putting them in another seat the is more appropriate), respect for the workers, along with other factors. 

Retaining employees can be accomplished through benefits, time off, respect, vested benefits, ownership interests, and several other ways. 

The importance of developing and keeping key people cannot be overlooked. 

  • Creates more business value
    • Purchasers of a business want to have middle management in place
    • Builds reputation and culture
    • Key people tend to impress other employees as a good example 
    • Key people, as described, are also likely purchasers of the business, or
    • Likely to run the business while the owner enjoys life, but still has the control and wealth

My suggestion to many small business owners over the years has been to find ways to build a key group as quickly as they can and to build the group around the values which the owners have. 

If you have an interest in learning other ways of keeping your key people, this video will be of value. 

Case Study #3. Corporate Executive Equity Plan (CEEP)

For A Free White Paper called, “Wealth Without Taxes”. Click


You As A Business Owner Have the Best Bank In Town!

WHO WANTS TO BUILD MORE WEALTH THROUGH THEIR BUSINESS?  

Did you know as a small business owner, have access to the best possible loan arrangements to create future wealth. This little know secret in the tax code, which has been used by large companies and savvy financial professionals for decades, allows you to use your company cash flow to create tax-free wealth, at a nominal tax cost.   

Take 10 minutes to see how $55,000 creates $1,875,000 of tax-free wealth.  

Wealth Without Taxes Report: Click For Your Report

The Easy Process To Identify and To Solve The Problems!

The Easy Process To Identify and To Solve The Problems!

Excerpts from My book, “Unlocking Your Business DNA”

The One Page Solution!

As we start the process of fixing the problems, they need to be identified. In chapter 1, I discussed how the business owner needs to find their “Business DNA”. Again, this is about focus and asking the right questions, and giving the business owners the amount of time, they need to think it through.

I break down the issues into two categories, BUSINESS GROWTH AND TRANSITION.

Business Growth: Focuses on the business itself such as the strategies needed to grow the business, the systems, the culture, and its employees. It is all about the business future.

Transition: Focuses on the categories that relate to the owners, and the changes they need to make in their personal life because the business is growing.

I keep these categories separate because the issues concerning the business growth are different than the owners transition issues. However, as the business growth changes, it affects the transition of the owners, and vice versa.

It is very important that the business owner is committed to fixing their problems.  If they are not, the first time they have a business roadblock, they will tend to put planning on the back burner.  This is a mistake, because most of the time it does not resurface until there is a crisis.

However, in our planning we do create action plans in small steps. Having a team of advisors working together creates the ability to complete the small steps needed to accomplish our goals.

An Example:

A perfect example was when a company we were working with had plateaued in growth and wanted to create more business growth. When we went through some of the planning questions, I realized the owner had spent no time systemizing their business.

The owner had no documentation of operational systems of his business, but instead it was all in his head. He would delegate the tasks to his employees like a drill sergeant.  He never even thought of the fact that there was no continuity in his business, consequently, if something happened to him, the business would have ended.

I asked him, “could you go on vacation for three months and not check in during that time”?

He looked at me and laughed, replying, “are you kidding this place would fold in seven days.”

I replied, at least you are real, the sad part however is you do not have a business, you have a job. You have a position, a paycheck, and a place to go, but you do not have a business.

He looked at me dazed! But he knew I was right.

The Process Using “One Page Solutions”, will keep everyone on track.

To uncover the issues and problems with the business owner we go over the main subjects called “ONE PAGE SOLUTIONS.”  On any subject there are always a few directions in which the business owner can go. We discuss them and analyze what are the most important subjects the business owner needs to deal with currently. “THE ONE PAGE SOLUTIONS” ARE LISTED BELOW.

Each Subject has a few sub-topics we review with the owners. As we DISCUSS the One Page Solutions, we find the strategies which will solve the issues. Once we are done with the subject, we move on to the next One Page Solution, if any.

THE FOCUS AREAS of the “One Page Solution” ARE:

1-Sale of Business (outside)/ Evaluation Methods/Timing

2- Inside Transition (Family, Co-Owners, or Key Employee/s)

3-Passive Ownership- Owner wants to still run the business, but take long trips

4-Retirement; defining and preparing

5-Wealth Accumulation & Asset Protection (both in and out of the business)

6-Premature Death- Consequences

7- Estate Distribution- updating

8- Life Insurance Contracts and Benefits

9-Legacy Planning / Management of Legacy

10-Disability and Illness, Medicare, and Medicaid

11-Key Employee Retention- and Creating A Culture

12-Key Employee Owner’s Manual- systematically creating company manual, business coaching, marketing proceedures

13-Corporate Benefits and Retirement- cost and efficiency

14-Qualified Plans and Personal Liabilities- Executive Compensation

15-Family Relationships/Employee Relationships/Human Resource

We helped a business owner recently with the problem of not having business growth over a prolonged period of time.  The solution was to put in place strategies that would create transferable values for the future.

They included things like creating key group, documentation, standard procedure, diversification, and growth strategies.

In this case we realized this will take some time to implement. The owner was under no delusion that this will be done in one year. Most importantly the owner started the process. A few years from now he will see the outcomes in all its glory. Because we have experts in our toolbox, we shared our professional advisors with our client for coaching purposes, and education.

Besides implementing a few systems, they will also do a business appraisal every two years. Over a period, this will help them evaluate the growth of their company by implementing the systems suggested.

By doing this the company could allow for better planning in the future, and adjust the path towards financial security, and business growth.

One of the key elements to helping Business owners solve problems is to also identify the roadblocks. This eliminates the surprise factor should our implementation strategy not go as planned. In one of our planning agendas, we discuss these roadblocks and try to define the subsequent issues and challenges in the future.

What is extremely important in this process is that it makes the owner aware of any potential issues they must have to deal with in the future and stay ahead of the problem curve.

Over the years what has been extremely helpful has been the communication with the team. Again, these are the client’s advisors that may or may not have been in place before we started planning. Since we update the team regularly, we are often given new advice that has been helpful in forecasting future events in the business.

We normally would not have this knowledge if we did not have the team of advisors in communication. This is one of the biggest advantages of working with the team and having periodic reviews.

We have been successful helping business owners work on their business to get issues resolved and to focus on details. We use a One-Hour a month system for the business owner to do this.  This allows the business owner the brevity they want, but also, gives them quality time to organize the details of their business. Through our step-by-step system, we help business owner cover all the key issues that are needed to cover to run your business smoothly, take more time off, earn more money and just enjoy working and life much better.  

If you would like a FREE WHITE PAPER called “Your Business Essential” which will help you organize your business, CLICK THE LINK BELOW, download the white paper. This is a 128-page guide in business planning Your Free. When you click submit on the form, your file will immediately download.  Enjoy. 

Immediate Download  

You can purchase of “Unlocking Your Business DNA”, AT Amazon. All profits to to Wounded Warrior Foundation and other Veteran groups.

Financial Leaks

If You Had a Financial Leak in Your Financial System, And It Was Going to Bust Your Financial Pipes and Bankrupt You, When Would You Want to Know About It?

Financial mistakes are made every day by many business owners without them realizing they cause leaks in their long-term plans until it is too late. 

This happened to my family 52 years ago. Because of it, I saw the devastation up close and personal. Obviously, I was so passionate about “financial mistakes,” I authored a book about it, and started a podcast to help business owners avoid making mistakes that resulted in major leaks in their lives.[i]

Many, if not most, business owners totally ignore the red flags which indicate the leaks, but go unattended, which ultimately break the pipes of the financial world of the business owner, leading to a swift exit from their businesses, and or bankruptcy. 

Having worked with business owners for many years, I have been up close and personal, to witness some of these financial mistakes. 

I am going to list several of them with the hopes they will make you more aware of the red flags when you see them. 

Mistakes and Leaks

#1. Depending on your Accountant and your Attorney for your long-term planning. 

Business owners assume by having an accountant and/ or a lawyer, they will be up to date on all the tax laws that affect them. False! Most CPAs and accountants provide specialized services and do them well. Accountant’s record history and put out tax fires if your mistake is fixable. Very few are trained in financial planning, or in-depth planning. If they are, they do not usually file tax returns for people, they are in another area of planning. 

Attorneys will keep you from doing things that may be illegal or ill-advised and create an unlawful situation in your personal and business life. They are not in the planning business, but normally in the reaction business. 

However, you may find an attorney who is proactive in planning, and looks at the whole picture, not only from the documents needed to fulfill your wishes, but also to the financial side of the equation. What good is it to have the greatest documents $10,000 can buy, but there isn’t enough cash in the estate to pay the taxes, or keep the survivors in the lifestyle you wanted them in?

#2. Not getting a certified evaluation of your business periodically. Instead, relying on formulas and fixed price values. 

If you think you know the value of your company all you need to do is look at the IRS cases where they have refuted the valuation the estate put on the business in tax court, and you will realize there is more to establishing a value on your company then just general formula.   Just because your competitor tells you they can sell their “like kind” business for 10 x earnings, doesn’t mean you can. Every business is different in its makeup and the way it is run. Consequently, so are the valuations.  I have been told by my clients;” they are using what the “association” uses for their members”? What? Do not drink the cool aid, use a certified appraiser for your appraisal and save yourself a lot of angst. 

#3. Not taking advantage of your company’s cash flow to create “executive compensation” benefits for you and your family. 

By not doing so, you are missing one of the greatest benefits your company can give to you. Your company checkbook can do much more for you and your family than your personal check book, and it is much more tax efficient. You can create a tax-free income for retirement on a fraction of the tax cost of what a pension plan would cost. Also, most of the executive benefits are not regulated by the IRS, giving you much more freedom as to how much you can save, and how long. 

#4. Not delegating responsibilities in your company. 

By not delegating tasks, you are depressing the future value of your company’s true selling price. Purchasers do not want you; they want a viable key group that knows how to run the business. By not delegating, you do not develop the key group, and potential employees that think like an owner, which is an asset for business’ growth and value. 

#5. Not systemizing the business and journalizing the systems. 

Having systems in your company, along with documentation creates a much higher purchase price of the business. A purchaser finds greater value by having a ready-made system which drives the running of your business. Systems and documentation must go together. 

#6. Not taking the time to plan your estate and incorporate your business planning. 

Who gets what, and when? What will it cost to transfer property to your family? What are the things you can do to mitigate the tax bite? Estate taxes are voluntary, and it is only the people who do not plan, who pay large taxes and estate fees. Are the family members ready to run a business? Who will run the business? These are only a few of the many questions business owners should be asking themselves. These are the areas an astute and excellent planner would ask questions about. The type of planning you do, will depend on your family, business, and estate situation. Without this type of planning, great financial pain and disruption in the business and the family can occur. 

#7. Not having an up-to-date transition and succession plan.

What will happen to your business when you retire, have a long-term illness, die, or just need to leave? What do you want to happen to it? Without a thought-out plan, there is a financial mistake and a financial leak. Since your business may make up most of your wealth, without a succession plan, you jeopardize the future value of the business along with the future financial security of the family and your loved ones. 

#8. Not having records of your business and your estate organized for your family should you die. 

You are not around, what did you want to happen to the estate and the business? Without instructions, the estate is lost as to what you wanted to happen to your business. Without instructions they do not have the permission to continue the business, pay certain bills, keep employees. At the very least, this is an area which you should have communication with your family, and documentation of instructions. 

#9. Not having a “Plan B transition,” when you have not completed a Plan A. 

So many business owners talk about having a plan of transition and succession, but never get around to getting it done. In this case you are better off having some plan, rather than not having any plan. This is the Plan B: “The JUST IN CASE PLAN.”  This is the plan that comes into effect if you were killed in a car accident on the way home from a party, but you did not have any formal plan, because all the unsigned papers were in your top drawer in your office, for the last three years, PLAN. GET my drift? 

#10. Having most of your sales come from only a few clients. 

Happens more than you can imagine, and you need to be aware of it. If this is the case, start acquiring more clients. The reasons are obvious. If you have more than 10% of your sales coming from one area, you should start acquiring more clients. What happens if that customer finds a better provider with lower prices? What happens if they are aware that you are dependent on their business? Again, it is obvious that this can be a problem if not changed. 

#11. Your professional advisors should be working as a team with each other for your benefit. 

In my book I discuss one of the best tools I used in planning for the business owners, which was having a periodic meeting with the other advisors to keep them in the loop. The benefit was to learn what they were doing for the owner, and to communicate to them, what I was doing. It helped to avoid overlapping. Also, I found that some of the members knew more about the owner’s likes and dislikes, which helped us understand their thinking, allowing the team to produce solutions that made sense and were workable. Ask yourself, how many times have all your professional advisors sat down in a room together to discuss your challenges and your dreams?

#12. Not sharing you planning with your spouse. 

It certainly makes it much easier when both spouses are on the same financial page. One of you will be the end user of your estate assets and it would be best for all parties to know what the long-range thinking is. Have a spousal business discussion periodically. It really helps. 

#13. Having the wrong type of business structure currently in your business career. 

Many times, the business structure you started with, is not the structure you should have currently. Over time, the business grows and outgrows the same business structure you started with. It could be another type of structure would be more effective for your current financial situation. I see many companies who should be an S corporation now, but have stayed in the original structure, only to pay more payroll taxes than they need too. The type of business structure you will use, is driven by tax planning and protection. It pays to discuss this aspect of your business as it may provide better protection and save taxes. Your accountant can guide you. 

#14. Not having a Buy and Sell Agreement/Business succession agreement. What is going to happen to the business at your death, or one of the seven triggers. 

You have a Buy and Sell Agreement (BSA); however, the agreement doesn’t discuss the funding of a triggering event. For example, if a partner died, life insurance would be the best choice to fund this triggering event because it would be the least expensive. However, other triggers, such as divorce, termination, bankruptcy, do not have vehicles to fund the event. The BSA must address how they will be funded? Many BSA do not address the funding of a particular trigger. Will there be a loan, a note, cash flow? It is best to discuss these areas while all the parties are living and involved. Keep in mind, that the BSA is a contract, and the parties of the agreement are liable for the payments to be made. 

#15. Not taking advantage of the income tax laws which allow you to spread some of the benefits to lower taxpayers in your family. 

Have your kids work for you and earn a salary? That salary will be at a lower cost and could be part of the funding for their college. Or changing your business structure to save taxes. As an example, becoming a S-Corp and taking a lower salary to avoid payroll taxes. There are many areas of the income tax law that favor family participation where there is a shifting of tax obligations. Your accountant would be a great resource to discuss this with. 

#16. Not taking adequate time away from your business. 

In my book (Unlocking Your Business DNA), I wrote about taking much more time off from your business. There are so many reasons to consider this. For example, I worked 80 days a year seeing clients. The other days, I worked on the business, but did not see clients, and this gave me more time freedom. This allows for more creative thinking, less stress, better family and employee relationships, and a host of other benefits. Many business owners can design this type of arrangement when they consider delegating and implementing systems in their business. This is also important for at least two reasons:  1-Employees can learn how to think like owners. 2- By taking time off you start to create great ideas for the growth of your business and help enhance your qualify of life. I call this the ideal business and personal lifestyle. 

One minute Survey assessment tool get your free Business Assessment using the One-Minute Assessment Tool. This tool will help you uncover potential mistakes and financial leaks you don’t even exists.  When you don’t know they may exist, you don’t have the choices of resolving them, or ignoring them like other KNOW MISTAKES.  This tool will do three things: 

  1. Make you aware of your current planning to this point good or bad!
  2. Make you aware of the financial mistakes planning we do.
  3. Help you formulate questions you may want to discuss

 CLICK HERE. For your One-Minute Survey


[i]“Unlocking Your Business DNA”, Thomas J. Perrone, CLU, CIC – AMAZON